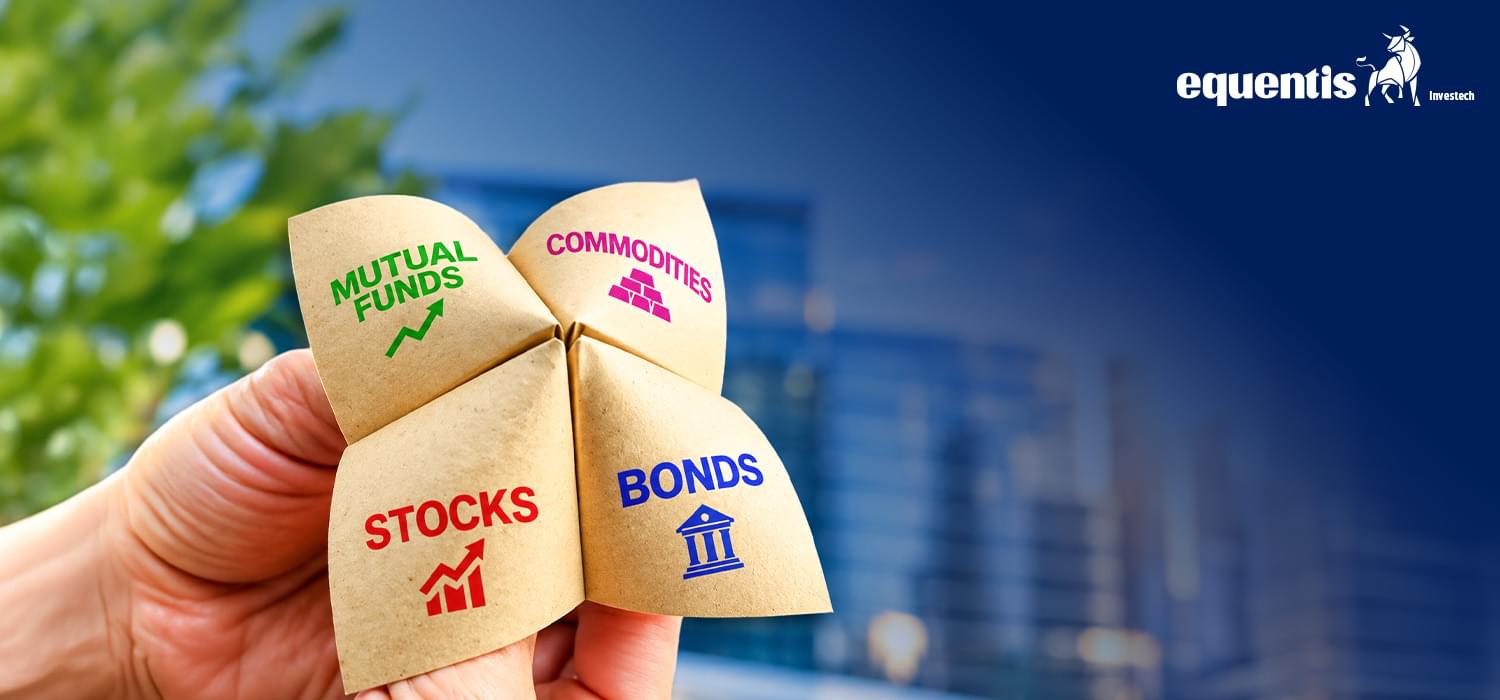
For a long time, building an investment portfolio seemed fairly straightforward. You had stocks for growth, bonds or fixed-income investments for stability, and perhaps gold or real estate for some additional diversification.
But as investors become more aware of different opportunities, alternative investments are becoming a bigger part of the conversation.
Private equity, private credit, real estate funds, infrastructure, venture capital, hedge funds and other private market investments can offer access to opportunities that traditional stocks and bonds may not provide.
That naturally leads to an important question: How much of your portfolio should actually be invested in alternatives?
The simple answer is that there is no universal percentage that works for everyone.
For one investor, 5% may be enough. Another investor with a larger portfolio, a longer time horizon and fewer liquidity needs may be comfortable with 15%, 20% or more.
The right number depends less on what others are investing and more on what your overall financial situation looks like.
What Are Alternative Investments?
Before deciding how much to invest, it helps to understand what we mean by “alternative investments.”
In simple terms, alternatives are investments that don’t fall neatly into traditional categories such as publicly traded stocks and bonds.
This can include private equity, venture capital, private credit, real estate, infrastructure, commodities, hedge funds and certain other private market investments. The exact definition can vary, but the common idea is that these investments offer exposure to assets or strategies beyond conventional public markets.
For Indian investors, Alternative Investment Funds, or AIFs, are one of the more commonly discussed routes into some of these opportunities. SEBI regulates AIFs and maintains a specific regulatory framework for them.
But just because an investment is called “alternative” doesn’t automatically make it better.
It simply means that it behaves differently from traditional investments, and that difference can be useful when building a diversified portfolio.
Why Are Investors Looking at Alternatives?
The biggest reason is diversification.
Imagine that most of your wealth is invested in listed equities. When the stock market falls sharply, a large part of your portfolio can fall at the same time.
Adding an investment whose performance is driven by different factors may help reduce your dependence on the public stock market.
For example, private credit may be driven more by lending terms and the credit quality of borrowers. Real estate may depend on rental income, property values and local demand. Private equity may depend on the growth and eventual sale of privately held businesses.
These investments don’t necessarily move in exactly the same way as listed stocks.
That is one of the main reasons alternatives can have a role in a diversified portfolio. The CFA Institute notes that alternatives can potentially serve different roles, including capital growth, income generation, diversification and, in some cases, inflation protection.
But More Alternatives Don’t Automatically Mean More Diversification
This is where investors need to be careful.
Buying five different alternative investments does not necessarily mean you have five completely different sources of risk.
For example, you could own a private equity fund that invests in real estate companies, a real estate fund and a listed real estate investment. On paper, these may look like different investments.
But there could still be significant exposure to the same underlying economic factors.
This is why diversification should not simply be about counting investments.
Instead, ask yourself:
“What is actually driving the returns of these investments?”
That question can give you a much better picture of how diversified your portfolio really is.
So, How Much Should You Allocate?
There is no magic number.
However, looking at different industry frameworks can give investors a broad sense of what is possible.
For example, J.P. Morgan Private Bank says it typically advises clients who have committed to private markets to consider allocating around 15% to 30% of investible funds to alternatives and other long-term illiquid assets, while noting that more conservative or liquidity-conscious investors may choose lower allocations.
That doesn’t mean every investor should put 15% to 30% of their money into alternatives.
In fact, that would be the wrong takeaway.
The important point is that the appropriate allocation can vary significantly depending on the investor.
Another analysis from Fidelity found that, based on its liquidity framework, allocations of up to 15% in private assets could be appropriate for some households with $1 million to $5 million in financial assets, while households with more than $5 million could potentially support allocations of up to 30%. It also notes that private allocations may not be appropriate for households with less than $1 million, depending on spending needs.
These figures are examples of institutional frameworks, not rules for individual investors.
Your own allocation needs to start with your financial goals.
A Smaller Allocation Can Still Make a Difference
You don’t need to invest a huge portion of your portfolio in alternatives to benefit from them.
For many investors, a smaller allocation can simply act as an additional layer of diversification.
For example, someone might decide that the majority of their portfolio should remain in traditional investments while keeping a smaller portion for alternatives.
The exact percentage will depend on the investor’s goals, risk tolerance and liquidity needs.
This approach can also make it easier to understand how the alternative investment behaves before increasing exposure.
After all, an investment may look attractive on paper, but living with an investment that cannot easily be sold is a different experience.
Your Liquidity Needs Matter More Than You Think
This is probably one of the most important things to consider before investing in alternatives.
With a listed stock or mutual fund, you generally have much easier access to your money.
Some private market investments are different.
Your money may be locked in for several years, and even when an investment has an exit mechanism, selling may not be as quick or straightforward as selling a listed security.
The CFA Institute highlights liquidity planning as a key consideration when investing in private alternatives. Fidelity also points out that illiquid investments can create problems if investors suddenly need cash or have to rebalance their portfolios.
This means you should ask yourself a simple question before investing:
“If I need this money next year, will I be able to get it?”
If the answer is no, you need to be comfortable leaving that money untouched for the required period.
Don’t Invest Your Emergency Money in Alternatives
Your emergency fund and short-term financial needs should not depend on an investment that may take years to exit.
Suppose you have money set aside for a house purchase in two years.
Putting that money into a long-term private investment simply because it has the potential to generate higher returns may create a problem.
The investment could still be doing perfectly well, but you may not be able to access the money when you need it.
This is why your portfolio should have enough liquid assets to handle your near-term needs before you start increasing your allocation to illiquid investments.
Your Investment Horizon Matters
Alternative investments often make more sense when you can think long term.
If you are investing money that you will need in two or three years, locking it into a long-term private investment may not be appropriate.
On the other hand, if you are investing money that you don’t expect to need for 10 or 15 years, you may have more flexibility.
The CFA Institute notes that investors with less than a 15-year investment horizon should generally avoid certain private real estate, private real asset and private equity funds because of their long-term and illiquid nature.
Again, this is not a rule that applies identically to every investment.
Different alternative investments have different structures.
But the larger lesson is simple:
Don’t invest long-term money into short-term goals, and don’t invest short-term money into long-term investments.
Your Age Alone Shouldn’t Decide the Allocation
It is tempting to say that younger investors should invest more in alternatives because they have more time.
But age is only one part of the picture.
Two people of the same age can have completely different financial situations.
One may have a stable income, a large emergency fund and substantial liquid investments.
The other may have irregular income, significant upcoming expenses and most of their wealth already tied up in property.
Giving both investors the same alternative allocation simply because they are the same age wouldn’t make much sense.
Your income, existing assets, liabilities, goals, liquidity needs and risk tolerance all matter.
Look at Your Existing Exposure First
This is another area where investors often make mistakes.
Before deciding how much to put into an AIF or another alternative investment, look at what you already own.
You may think you have a diversified portfolio because you own equity funds, property and an alternative investment.
But perhaps a large portion of your wealth is already sitting in your family’s real estate business.
In that case, adding another real estate-focused investment could actually increase your concentration.
The same applies to business owners.
If most of your personal wealth is tied to one private company, investing heavily in private equity or similar opportunities may increase your exposure to risks that you already have.
The right question isn’t simply:
“How much should I put into alternatives?”
It is:
“How much additional alternative exposure can my overall financial situation comfortably handle?”
Don’t Chase Alternatives Just Because They Promise Higher Returns
This is perhaps the biggest mistake investors can make.
An alternative investment may advertise an attractive return potential.
But higher potential returns usually come with additional risks, complexity or restrictions.
Alternatives can have limited transparency, higher fees, uneven performance between managers and significant liquidity constraints. J.P. Morgan also highlights illiquidity, dispersion in returns, limited transparency, tail risks and complex fee structures as important challenges in private market investing.
So don’t invest simply because someone tells you that an alternative investment can generate better returns than a traditional investment.
First understand where those returns are supposed to come from.
Then ask what could go wrong.
Alternatives Should Have a Job in Your Portfolio
A useful way to think about alternatives is to give each investment a specific purpose.
Maybe you are looking for long-term capital growth.
Maybe you want income.
Maybe you want exposure to real assets.
Maybe you want to diversify away from listed equities.
Once you know the purpose, it becomes easier to decide whether an alternative investment actually belongs in your portfolio.
The CFA Institute similarly describes different roles for alternatives, including growth, income, diversification and inflation-related protection.
If you cannot explain why you own an investment beyond “someone said it will give good returns,” it may be worth reconsidering.
A Simple Way to Think About Your Allocation
Instead of starting with a percentage, start with three questions.
First, how much money can I afford to keep invested for a long period?
This gives you an idea of your liquidity capacity.
Second, what risks do I already have in my portfolio?
This helps you understand whether the alternative investment is actually adding diversification or simply adding more of the same risk.
Third, what role do I want the alternative investment to play?
Is it for growth, income, diversification or something else?
Once you answer these questions, you can start thinking about the appropriate allocation.
The percentage should come after the strategy, not before it.
What About HNIs and Wealthy Investors?
Investors with larger portfolios often have greater flexibility when considering alternatives.
If you have significant liquid wealth and don’t need to access a large part of your portfolio in the near future, you may be able to handle more illiquid investments.
This is one reason alternatives tend to feature more prominently in family offices and institutional portfolios.
But having more money does not eliminate investment risk.
In fact, larger portfolios can sometimes become more complicated because they may contain businesses, real estate, private investments, public equities, bonds and other assets at the same time.
The challenge then becomes managing the portfolio as a whole rather than looking at every investment separately.
The Bottom Line
So, how much of your portfolio should be in alternative investments?
There is no single answer.
For some investors, alternatives may make sense as a small allocation. Others with higher liquidity capacity, longer investment horizons and larger portfolios may be comfortable with a more meaningful allocation.
What matters is not whether you have 5%, 10%, 20% or 30% in alternatives.
What matters is whether that allocation fits into the rest of your financial plan.
Before investing, look at your liquidity needs, investment horizon, existing portfolio, risk tolerance and financial goals. Understand what the alternative investment actually owns, how it generates returns, what the fees are and how easily you can exit.
Most importantly, don’t treat alternative investments as a shortcut to higher returns.
They are simply another set of tools available to investors.
Used thoughtfully, they can potentially add diversification, new sources of income and exposure to opportunities outside traditional markets. Used without understanding their risks, they can make an already complicated portfolio even harder to manage.
For investors exploring alternatives, the goal should therefore not be “How much can I put into alternatives?”
It should be:
“How much can I invest without compromising the rest of my financial plan?”
That is a much better starting point for building a portfolio designed not just to grow wealth, but to manage it over the long term.
Read More: Investment mistakes that can Delay financial freedom