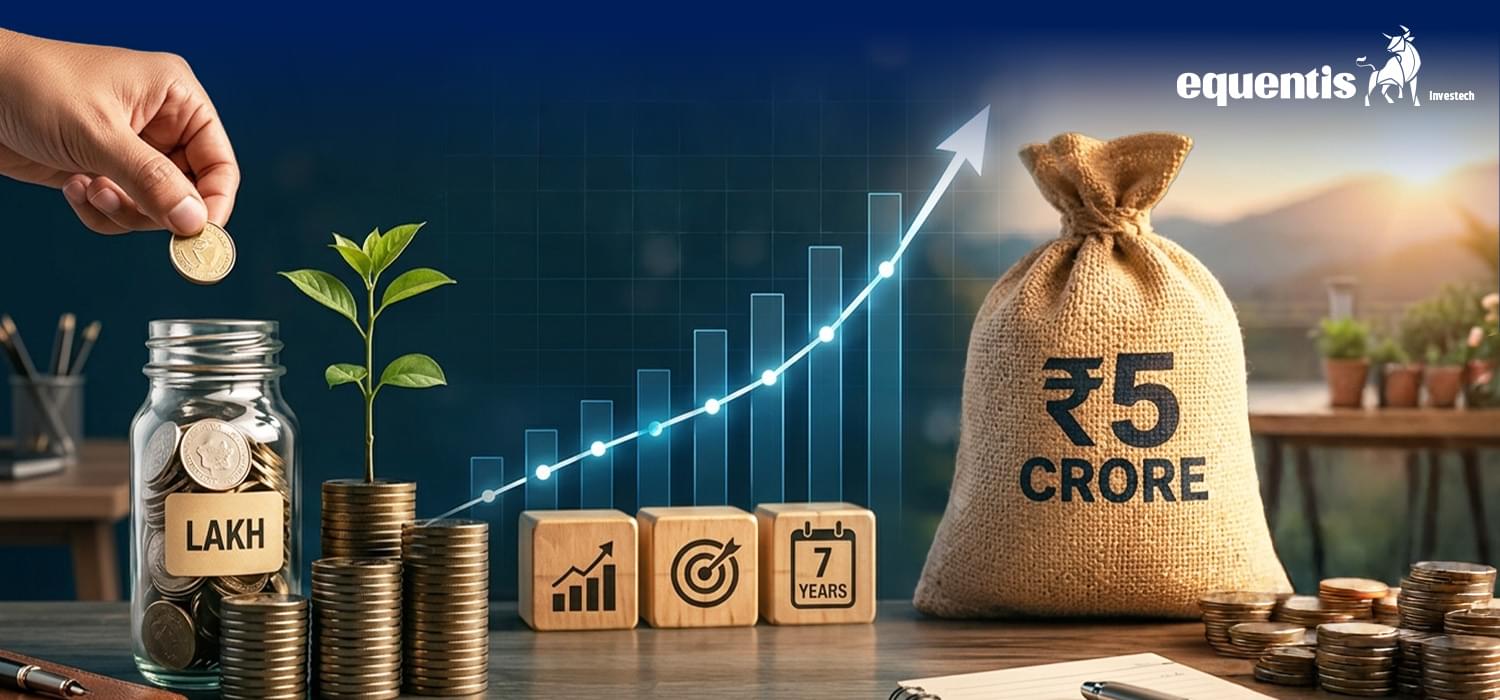
Building a ₹5 crore investment portfolio can feel like an impossible target.
For someone starting with a small investment, ₹5 crore may seem far away. But wealth creation is rarely about reaching a large number through one extraordinary investment.
It is usually about making smaller, sensible decisions consistently over a long period of time.
The combination of regular investing, compounding, asset allocation and patience can make a significant difference.
More importantly, building a ₹5 crore portfolio does not mean you have to constantly search for the next multibagger stock.
You need a plan that can work through different market conditions.
So, how do you actually build a ₹5 crore investment portfolio?
Let’s look at a practical roadmap.
Start With Your ₹5 Crore Goal
Before deciding where to invest, understand what you are actually trying to achieve.
A ₹5 crore target can look very different depending on where you are starting.
Someone with ₹10 lakh invested today will have a different journey from someone who already has ₹1 crore.
Your age also matters.
So does your income, savings rate, investment horizon and ability to handle market fluctuations.
This is why there is no single investment strategy that can take every investor to ₹5 crore.
The first step is to understand your own starting point.
Once you know where you stand, you can work backwards and determine how much you need to invest and for how long.
The Three Things That Drive Wealth Creation
There are three major factors that influence how quickly your portfolio can grow.
The first is how much you invest.
The second is how long you stay invested.
The third is the return generated by your investments.
Most investors focus heavily on the third factor.
They want to find investments that can deliver higher returns.
But the first two factors are often more controllable.
You can increase your investment amount as your income grows.
You can also give your investments more time to compound.
Trying to compensate for a short investment horizon by taking excessive risk can be dangerous.
Compounding Can Change the Equation
Compounding is one of the biggest reasons why starting early can matter so much.
When your investments generate returns, those returns remain invested and can generate further returns.
Over long periods, this creates a snowball effect.
For example, imagine you invest ₹25 lakh and your portfolio generates a hypothetical 12% annual return.
After 10 years, the investment could grow to around ₹77.6 lakh.
After 20 years, it could become roughly ₹2.4 crore.
After 25 years, it could approach ₹4.25 crore.
These figures are only illustrations. Investment returns are not fixed or guaranteed.
But they demonstrate an important point.
Time can dramatically change the outcome of an investment.
This is why investors should think about wealth creation as a long-term process rather than a race.
How Much Do You Need to Invest?
The amount you need to invest depends on your starting capital and timeline.
If you are starting from zero, reaching ₹5 crore in 10 years would require a much higher investment than reaching the same target in 20 or 25 years.
This is where financial planning becomes useful.
Instead of randomly deciding to invest ₹20,000 or ₹50,000 every month, work backwards from your goal.
Estimate your investment horizon.
Estimate a reasonable long-term return assumption.
Then calculate the approximate monthly investment required.
For example, assuming a hypothetical 12% annual return, investing around ₹50,000 every month for 20 years could build a corpus of roughly ₹5 crore.
However, this should not be treated as a promise or prediction of returns.
Actual market returns can be higher or lower, and the journey will rarely be smooth.
The larger lesson is that extending your investment horizon can significantly reduce the monthly amount required.
Don’t Depend on Returns Alone
One of the biggest mistakes investors make is trying to reach their target by taking more and more risk.
Suppose an investor believes that a particular stock can deliver 30% returns.
They may start putting a large part of their portfolio into that stock because they want to reach ₹5 crore faster.
The problem is that higher potential returns usually come with higher risk.
If the investment falls sharply, years of savings can be affected.
Instead of asking, “How can I get the highest possible return?”
Ask:
“What return can I reasonably target without taking unnecessary risk?”
This small change in thinking can lead to better long-term decisions.
Build a Diversified Portfolio
Once your goal is clear, the next question is where your money should go.
This is where diversification becomes important.
A ₹5 crore portfolio does not have to consist entirely of stocks.
Depending on your goals and risk profile, your portfolio may include equity, debt, fixed-income investments, gold and other suitable assets.
Equity can provide long-term growth potential.
Debt and fixed-income investments can provide stability and help manage portfolio risk.
Gold may provide diversification during certain market conditions.
The exact allocation should depend on your individual financial circumstances.
There is no perfect asset allocation that works for everyone.
Let Equity Drive Long-Term Growth
For investors with a long investment horizon, equity can play an important role in wealth creation.
Businesses grow.
Corporate earnings can increase.
The economy can expand.
Equity investors participate in this growth through ownership of companies.
But equity markets can also be unpredictable in the short term.
A portfolio that is heavily invested in equities can fall significantly during a market correction.
This is why equity should be selected based on your ability to handle volatility.
For many investors, diversified equity mutual funds or index funds can provide broad market exposure without requiring them to select individual stocks.
Those who invest directly in stocks need to understand the businesses they own and accept the additional risks involved.
Don’t Ignore the Role of Debt
Growth is important when you are building wealth.
But stability matters too.
Debt and fixed-income investments can help reduce overall portfolio volatility.
They can also become increasingly important as you get closer to your financial goal.
Consider an investor who starts building a portfolio at age 30.
They may have several decades before they need the money.
Their portfolio can potentially accommodate greater equity exposure.
Now consider someone who is 58 and already has ₹4.5 crore.
Their priority may no longer be maximum growth.
Protecting the wealth they have already accumulated may become more important.
Your asset allocation should therefore evolve as your financial situation changes.
Increase Your Investments With Your Income
Your investment journey does not have to depend entirely on your starting monthly investment.
As your income increases, your investments can increase too.
This is known as a step-up approach.
Suppose you start investing ₹30,000 every month.
A few years later, your salary increases.
Instead of allowing your expenses to rise at the same pace, you could direct part of that additional income towards investments.
Your monthly investment might increase to ₹35,000.
Then ₹40,000.
Then ₹50,000.
Over a long period, these increases can have a meaningful impact on your final corpus.
This is particularly useful for young investors whose income is likely to grow over their careers.
Keep Your Emergency Money Separate
Your long-term investment portfolio should not be your emergency fund.
Unexpected expenses can happen at any time.
You may face a job loss, a major family expense or an urgent financial requirement.
If all your money is invested, you may be forced to sell investments when markets are falling.
That can damage your long-term wealth creation plan.
Maintaining an appropriate emergency fund gives your investment portfolio more room to stay invested.
It also reduces the need to make emotional financial decisions during difficult periods.
Don’t Make Your Portfolio Too Complicated
As investors learn more about markets, they often start adding more investments.
One mutual fund becomes five.
Five stocks become fifteen.
Then come sector funds, thematic funds, international investments and other opportunities.
Eventually, the portfolio becomes difficult to understand.
More investments do not automatically mean better diversification.
You could own several funds that have significant exposure to the same companies.
The goal should be to build a portfolio that is diversified but understandable.
Every investment should have a clear purpose.
If you cannot explain why you own something, it may be worth reviewing whether it belongs in your portfolio.
Rebalancing Keeps the Strategy on Track
Your portfolio will not remain at its original allocation forever.
Markets move.
Some investments rise faster than others.
Suppose you start with 70% equity and 30% debt.
A strong equity market could push your equity allocation to 80%.
Your portfolio is now more aggressive than you originally intended.
Rebalancing allows you to bring the portfolio closer to your target allocation.
It is not about predicting what the market will do next.
It is about maintaining the level of risk you originally decided you were comfortable with.
Regular portfolio reviews can help you identify when your allocation has moved significantly away from your plan.
The Biggest Threat May Be Your Own Behaviour
Market volatility is unavoidable.
Investor behaviour, however, can make its impact worse.
When markets are rising, investors often become more confident.
They may start chasing stocks that have already delivered strong returns.
When markets fall, the same investors may panic and sell.
Both decisions can hurt long-term wealth creation.
Building a ₹5 crore portfolio requires patience.
There will be years when your portfolio performs well.
There will also be years when the value of your investments falls.
A temporary decline does not necessarily mean that your long-term strategy has failed.
The important question is whether the investment still fits your financial plan.
What Happens After You Reach ₹5 Crore?
Reaching ₹5 crore is a major milestone.
But it does not automatically mean that you can stop thinking about your finances.
Your strategy may need to change once you reach the target.
During the accumulation stage, the focus is primarily on growing your wealth.
After reaching ₹5 crore, the focus may gradually shift towards protecting capital, generating income and meeting future financial needs.
For someone who reaches ₹5 crore at 40, the strategy may look very different from someone who reaches the same amount at 60.
The target is therefore not just a number.
It should be connected to what the money is supposed to achieve.
₹5 Crore Is a Milestone, Not a Shortcut
There is no guaranteed formula for building a ₹5 crore portfolio.
There is no investment that can promise to take you there quickly.
And there is no need to constantly chase the highest-returning asset.
A better approach is to build a system that you can follow for years.
Start with a realistic target.
Understand your current financial position.
Invest regularly.
Increase your contributions as your income grows.
Choose an asset allocation that matches your risk tolerance.
Diversify without overcomplicating your portfolio.
Review and rebalance when necessary.
Most importantly, give your investments enough time to compound.
Final Thoughts
A ₹5 crore investment portfolio may look like a massive financial goal today.
But large financial goals are built through smaller decisions repeated over long periods.
The investor who consistently saves, invests and stays disciplined can potentially give compounding the time it needs to work.
The journey will not always be comfortable.
Markets will fall.
Returns will vary.
Your financial circumstances may change.
Your portfolio will need adjustments along the way.
That is normal.
The goal is not to build a perfect portfolio.
It is to build a resilient portfolio that can keep working towards your financial goals through different market cycles.
₹5 crore is simply the destination.
The real strategy lies in how you get there.